FileHousing
Paying Someone to Clean the Gutters? Who Employs the Person on the Ladder Decides Your Exposure
Four ways to buy the same recurring upkeep job, and why the worker's employment status, not the quoted price, sets what you are exposed to.
- ByDesmond Falk
- Cut10/10/26
- Length1,010 words
- Read4 min
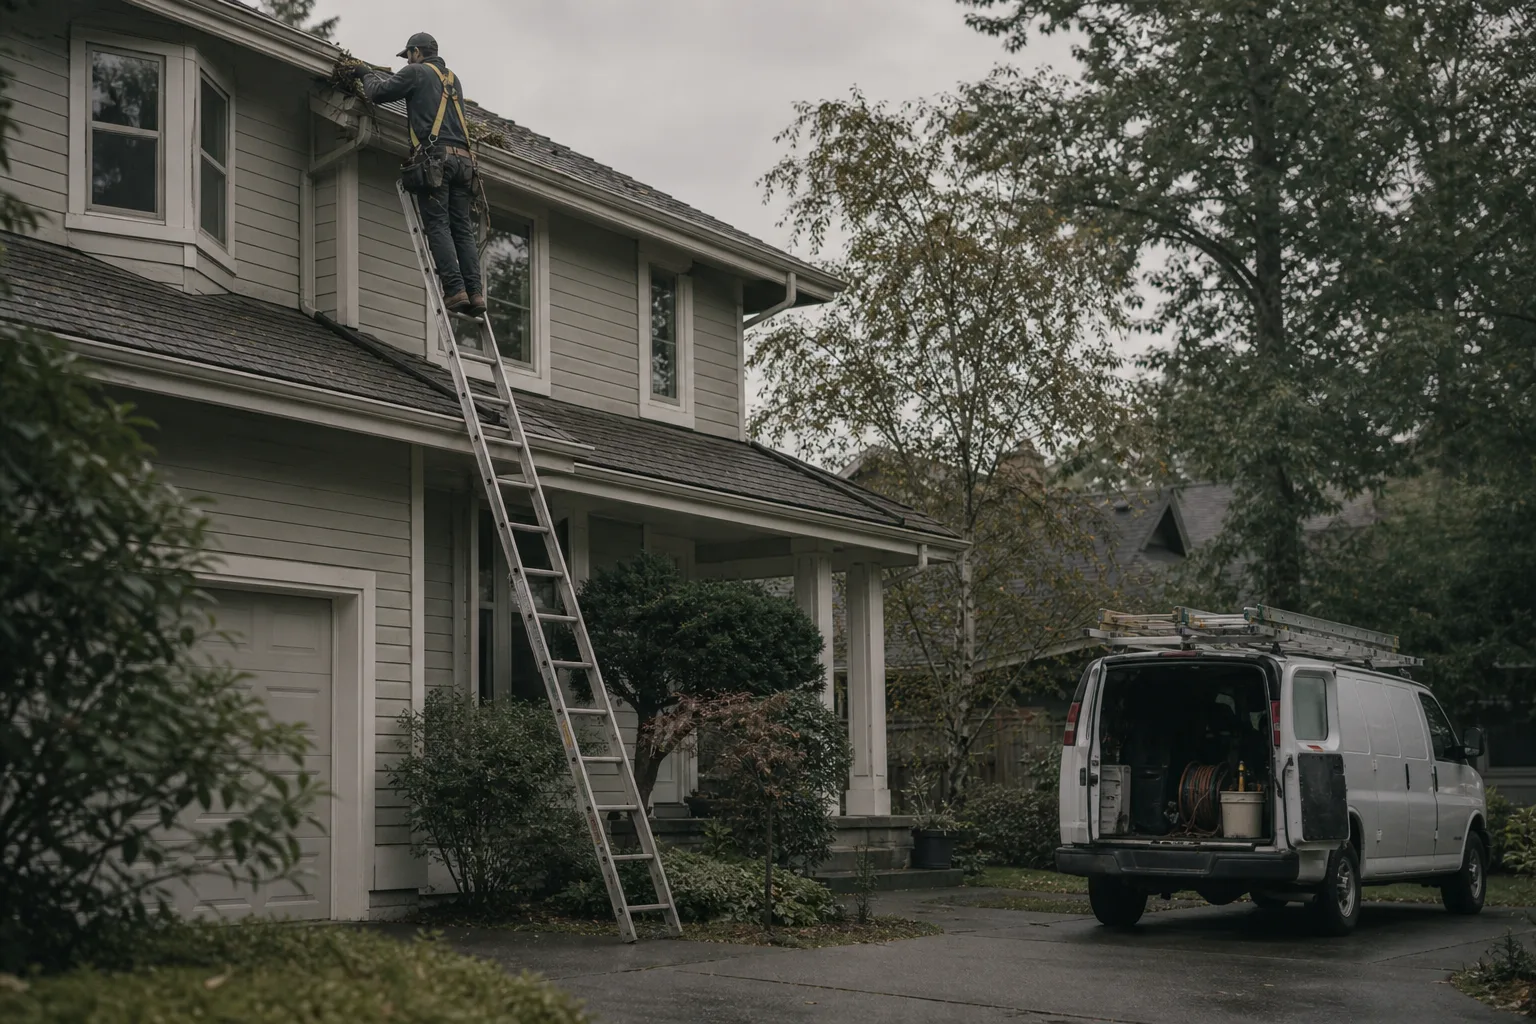
The recurring jobs are the ones that decide what a house costs to own. Gutters twice a year, dryer vent annually, chimney before the season, windows and siding on whatever cycle the climate dictates, ducts occasionally. None of them is expensive on its own. Over a decade they add up to more than most single renovations, and the way you buy them matters more than the line item suggests. The usual comparison is price and scheduling. The more useful comparison is who employs the person who climbs the ladder, because that answer, not the invoice, determines what happens when something goes wrong.
Four routes to the same gutter cleaning
The same task can be purchased in at least four structurally different ways, and the differences are invisible on the quote.
| Route | Who employs the worker | Typical insurance posture | Your recourse |
|---|---|---|---|
| National franchise | Local franchisee, usually as W-2 employees | General liability and workers' compensation carried at the franchise level, verifiable | Franchisee first, brand standards as backstop, written warranty on the work |
| Local independent company | Owner, with employees or subcontracted crews | Varies widely; may carry full coverage or may subcontract and carry little | Direct, often fast, depends entirely on the firm's solvency and coverage |
| App or marketplace platform | Nobody. The worker is contracting with you through an intermediary | Platform guarantee with caps, conditions and a claims window | Platform's dispute process, within its stated limits |
| Direct hire of an individual | Potentially you | Whatever the individual carries, which is frequently nothing | Small claims court, or your own homeowners policy |
Each of these is a legitimate way to get gutters cleaned. They are not interchangeable once a ladder slips or a downspout gets torn off a fascia board.
The overlooked party is the worker, and their status is your exposure
Most homeowners evaluate the transaction as two parties: themselves and the company. There is a third, and they are the one at height. The Occupational Safety and Health Administration oversees workplace safety standards in the United States, including ladder and fall protection requirements for people working above ground level. Those standards attach to employers. When a cleaning company sends a W-2 employee to your roofline, the employer carries the obligation and the workers' compensation coverage that pays if that person is hurt. When the person on the ladder is an independent contractor, or a worker a company quietly subcontracted after quoting you, that chain is weaker. And when you hire an individual directly, the question of who is responsible for an injury on your property can land on your homeowners policy, which typically includes a modest medical payments limit and a liability section never designed to absorb a serious fall.
This is why the status question is worth asking out loud before the first visit. It is a short conversation. Are your crews employees or subcontractors? Do you carry workers' compensation? Who shows up if the regular crew is booked?
Licensed, bonded and insured are three separate claims
The phrase appears on nearly every van. The three words do different work.
- Licensed. For general cleaning, many states require nothing. For chimney work, duct work, pressure washing near a septic field or anything touching electrical or gas appliances, licensing rules differ by state and sometimes by municipality. Check the state's licensing board rather than the company's website.
- Bonded. A surety bond typically protects against theft or failure to complete, up to a stated amount, and claims run through the bonding company. It is not insurance for property damage.
- Insured. General liability covers damage the company causes to your property. Workers' compensation covers injury to their people. A firm can carry one and not the other.
The practical step is to ask for a certificate of insurance sent directly from the agent, not a photocopy from the contractor's glovebox, and to confirm the policy is current on the date of the work. Some homeowners ask to be listed as a certificate holder, which means the insurer notifies them if the policy lapses. For recurring annual work, that notification is worth more than it sounds.
When the direct hire makes you an employer
A cleaner who comes every other week, uses your supplies, works hours you set and takes direction from you may be a household employee rather than an independent contractor. The IRS publishes the tests and the annual wage thresholds that trigger household employment tax obligations, including Social Security and Medicare withholding and reporting on your own return. The distinction turns on control over how the work is done, not on what either party calls the arrangement or whether payment is in cash.
For most upkeep jobs on this list, the work is episodic and the worker brings their own equipment, which usually sits well outside household employment. The recurring interior cleaner is the common exception, and it is the one where households most often drift into an arrangement they have not priced. Handled deliberately, with a payroll service or a clear contractor relationship, it is straightforward and the cost is predictable. Handled by default, it is a back tax question discovered later.
Reading the choice over ten years, not one visit
Price differences across the four routes tend to be smaller than the structural differences. A franchise often quotes high and absorbs the overhead of real coverage. A direct hire quotes low because the coverage is not there. The platform sits in between and caps its own exposure.
Over a long holding period, the sensible pattern most owners land on is a split. Anything involving height, fire, gas or water intrusion goes to an insured company with employees, where the quoted premium buys a counterparty who can pay for a mistake. Ground-level, low-consequence work goes wherever is convenient and cheap. Ask who employs the worker once, write the answer down, and the question does not need revisiting for years.
The folder that holds those certificates is doing quiet work. When a fascia board comes off in year six, the name of an insurer and a policy number turns a long argument into a phone call.